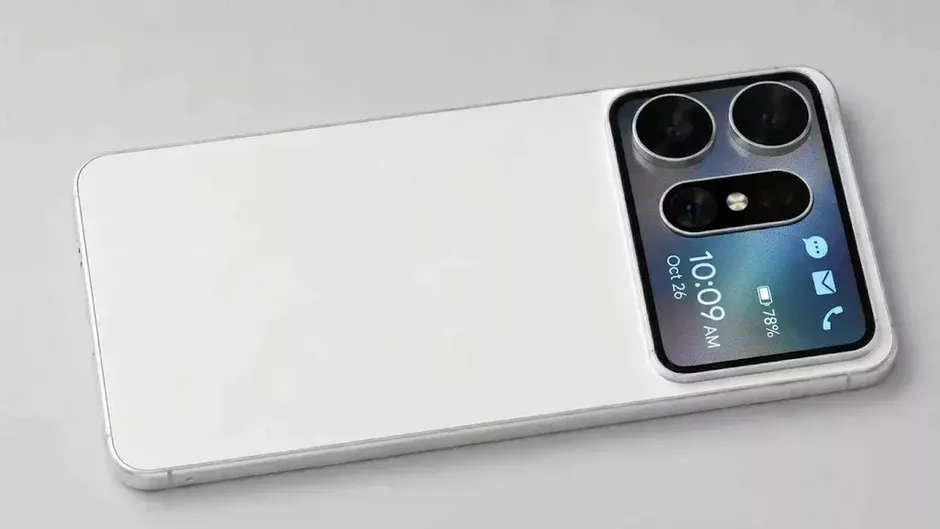
The global smartphone market is undergoing a fascinating psychological and structural realignment as recent industry data reveals that consumers are looking beyond the heavily marketed foldable phone sector for their next device upgrades. While technology giants have poured billions of dollars into refining hinges, flexible ultra-thin glass, and complex multi-layered displays, a broad cross-section of global tech consumers has signaled a strong counter-trend. Instead of embracing the high-cost, high-maintenance world of foldable devices, a significant majority of smartphone buyers are expressing profound enthusiasm for a classic form factor infused with a clever modern twist: conventional slab smartphones equipped with secondary rear displays integrated directly into the camera module.
This market insight, brought to light by a comprehensive industry opinion poll published in November 2026, challenges the long-held assumption that innovation in the mobile sector must inherently equate to a folding chassis. As manufacturers search for ways to revitalize stagnant standard designs, the integration of secondary OLED panels positioned near the primary camera housing has emerged as a surprisingly resonant concept. Far from being a fleeting gimmick of the past, this design ideology is capturing the imagination of everyday users who desire the functional benefits of secondary screens without compromising the structural integrity, battery performance, or price point of a traditional candy-bar phone.
The Anatomy of the Trend: Unpacking the November 2026 Survey Data
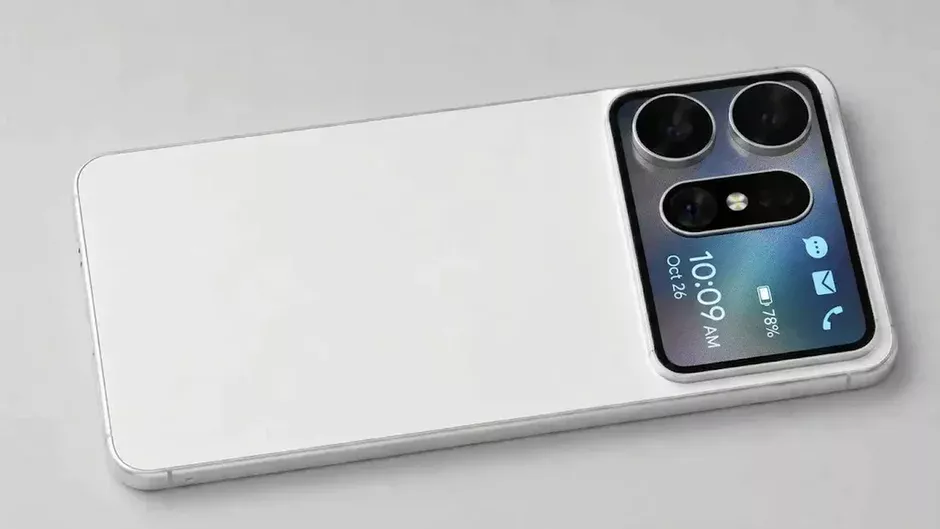
The data underpinning this shifting consumer sentiment stems from a large-scale public poll conducted by prominent technology publication PhoneArena, which gathered opinions from over one thousand dedicated tech enthusiasts and everyday mobile consumers. The results of the poll painted a vivid picture of what modern users truly value in their hardware. When presented with the concept of a standard slab smartphone featuring an auxiliary OLED screen nestled within the rear camera bump—a design language recently popularized by experimental global rollouts such as the Honor 700 series—the response was overwhelmingly positive.
According to the detailed breakdown of the survey metrics, more than half of all participating respondents stated that they actively love the design concept and would eagerly purchase a smartphone featuring an exterior rear secondary display. An additional 33 percent of voters expressed conditional support, noting that they would welcome a rear secondary screen provided that it was backed by genuinely useful software integration and practical daily utilities. Meanwhile, only a negligible fraction of the surveyed demographic claimed to have zero interest in supplementary displays, proving that the appetite for rear screens spans across the vast majority of the consumer base.
This high level of approval highlights a critical disconnect between what manufacturers frequently prioritize—expensive foldable engineering—and what a massive segment of the market actually wants: durable, reliable, and functionally enhanced everyday devices.
Evolution of the Dual-Screen Concept: From Novelty to Practical Utility
The integration of secondary screens on mobile devices is not entirely new, but previous iterations often suffered from poor software optimization, lack of developer support, or gimmicky implementations that drained battery life without offering tangible benefits. In the early days of dual-screen experimentation, secondary panels were frequently relegated to rugged niche devices or ultra-premium, experimental flagships that commanded exorbitant price tags.
However, the current generation of secondary screen integration borrows heavily from the tried-and-tested utility of the cover screens found on modern flip-style foldables. Just as users of vertically folding devices rely on external panels to manage their digital lives without unfolding their phones, the new wave of rear-screen slab phones offers identical efficiencies. Users can monitor urgent notifications at a glance, check incoming messages, control media playback, and manage phone calls without ever needing to wake the primary power-hungry display. Furthermore, these secondary panels allow for highly efficient Always-On Display (AOD) implementations, utilizing minimal power to display time, date, and critical system statuses.
One of the most compelling practical applications of the rear secondary screen lies in mobile photography. By functioning as a high-resolution viewfinder for the main camera array, the rear display allows users to capture professional-grade selfies using the primary, high-performance rear sensors rather than settling for inferior front-facing punch-hole cameras. This capability alone has proven to be a major selling point for content creators and casual users alike, bridging the gap between hardware performance and user-friendly ergonomics.
Industry Context and the Search for Relief from Form-Factor Fatigue
The rise of the rear-screen slab phone comes at a time when industry analysts have noted a growing sense of form-factor fatigue among global consumers. For nearly a decade, the standard smartphone industry has settled into a predictable rhythm of incremental updates: slightly thinner bezels, faster refresh rates, and marginal camera bumps that grow larger with each successive generation. While these internal upgrades are welcome, the external physical experience of using a standard rectangular slab has remained largely monotonous.
For consumers unwilling or unable to invest in expensive horizontal or vertical foldables—devices that still carry steep price premiums, delicate mechanical components, and compromises in battery capacity—the rear-screen slab phone offers an ideal middle ground. It introduces a fresh tactile and visual identity, provides genuine multitasking and utility advantages, and maintains the rugged durability and accessible pricing structure of traditional smartphones.
Industry watchers and market researchers suggest that this design philosophy represents a calculated response by hardware designers to combat market saturation. By finding innovative ways to utilize previously dead space—specifically the expansive camera modules required for modern multi-lens arrays—manufacturers can deliver differentiated products without having to redesign the core chassis from scratch.
Chronology of the Trend and Early Market Indicators
The journey toward mainstream acceptance of rear secondary screens has been gradual, marked by several key developmental milestones across the global supply chain:
- Early Experimental Phase (2020–2022): Several Chinese original equipment manufacturers (OEMs) experimented with rear secondary displays, often utilizing leftover smartwatch panels or small OLED strips on ultra-premium flagship devices. These early attempts were largely viewed as marketing novelties due to fragmented software ecosystems.
- Refinement and Camera Module Integration (2023–2025): As camera bumps grew significantly larger to accommodate periscope lenses and massive primary sensors, manufacturers realized that the surrounding housing offered an ideal real estate opportunity for discreet, flush-mounted secondary displays.
- Mainstream Prototyping and Regional Launches (Late 2025–Early 2026): Devices such as the Honor 700 series introduced integrated mini-screens within the camera module to regional markets, proving that the concept could be mass-produced efficiently while maintaining sleek aesthetic standards.
- Consumer Validation (November 2026): Industry polls, such as the comprehensive PhoneArena survey, formally quantified consumer sentiment, proving that public demand for rear-screen slab phones extends far beyond early adopters into the mainstream buyer demographic.
Expert Analysis: Economic and Technological Implications
From an economic perspective, the pivot toward rear-screen slab phones makes profound sense for both manufacturers and consumers. Developing foldable display technology requires immense capital expenditure, specialized manufacturing facilities, and intricate supply chains, which inevitably trickles down into high retail prices that alienate budget-conscious buyers. In contrast, incorporating a secondary static OLED panel onto the rear of a traditional glass-and-aluminum slab leverages existing, highly optimized manufacturing processes.
Technically, the engineering challenges of a rear secondary screen are far more manageable than those of a flexible display. Thermal management, battery degradation, and drop-resistance are significantly easier to solve when the chassis remains rigid. Analysts predict that component costs for secondary rear panels will continue to drop, making it feasible for brands to introduce these features into mid-range and upper-mid-range smartphone tiers within the next several product cycles.
Furthermore, software developers are finding it increasingly straightforward to adapt user interfaces for small, secondary rectangular or circular displays, thanks to standardized design kits provided by major mobile operating system developers. This ecosystem readiness ensures that users will not face the software fragmentation issues that plagued early dual-screen attempts.
Broader Market Impact and Future Outlook
As the mobile industry looks ahead to upcoming product launch cycles, the strong consumer backing revealed in recent market data is expected to embolden major global manufacturers. While foldables will undoubtedly retain their status as halo products for tech enthusiasts and enterprise executives, the traditional slab phone is far from obsolete.
By breathing new life into the conventional form factor through thoughtful innovations like rear secondary displays, hardware brands are proving that creativity in mobile design does not require a hinge. If current consumer sentiment translates into retail sales as predicted by industry observers, the next generation of global smartphones may very well feature a secondary screen as a standard point of distinction in an otherwise crowded marketplace.

