Apple Inc. is reportedly laying the groundwork for a major display transition across its tablet ecosystem, with industry supply chain reports indicating that Samsung Display is poised to become the primary supplier of OLED panels for the next-generation iPad Air. Expected to launch in the first half of 2027, the upcoming iPad Air lineup is anticipated to represent a significant technological milestone for Apple’s mid-tier tablet segment, bringing self-emissive display technology to a broader consumer base.
According to comprehensive insights gathered from global display supply chain monitors, Apple has mapped out production requirements for two distinct iPad Air screen sizes: an 11-inch variant and a larger 13-inch model. Throughout 2027, the cumulative demand for OLED panels dedicated solely to this device family is projected to range between 4 million and 5 million units. While Samsung Display is slated to capture the lion’s share of this lucrative manufacturing contract, Chinese display manufacturing giant BOE is actively pursuing a secondary supplier role, pending rigorous quality assurance evaluations by Apple.
As is customary for the Cupertino-based technology giant, Apple has not yet issued an official corporate announcement regarding the release schedule, technical specifications, or vendor allocations for the prospective OLED iPad Air. Consequently, all circulating metrics concerning production volumes, delivery timelines, and supply chain divisions remain strictly within the realm of industry projections rather than confirmed commercial agreements. Nevertheless, the unfolding supply chain dynamics offer a clear window into Apple’s long-term hardware roadmap and its ongoing efforts to diversify component sourcing while maintaining stringent quality benchmarks.
Strategic Vendor Dynamics and Supply Chain Landscape
The rumored distribution of panel orders for the 2027 iPad Air underscores the complex balancing act Apple maintains among its panel manufacturing partners. Samsung Display, a longtime pioneer and market leader in small- and medium-sized OLED panels, holds a dominant position in this latest supply chain cycle. Industry analysts note that Samsung’s advanced manufacturing infrastructure, high yield rates, and proven track record with Apple’s high-end iPhone and iPad Pro displays make it the safest and most reliable partner to shoulder the bulk of the initial production burden.
Simultaneously, BOE continues its persistent campaign to deepen its integration into Apple’s premium hardware ecosystem. The Chinese manufacturer is reportedly vying to supply panels for at least one of the two planned iPad Air sizes, utilizing its advanced B12 production facility located in Chongqing, China. The B12 plant houses sophisticated sixth-generation OLED production lines specifically configured to meet high-density mobile and tablet manufacturing demands.
However, securing the contract is far from guaranteed. Before achieving commercial mass-production approval, BOE must successfully navigate Apple’s notoriously rigorous quality control and technical evaluation processes. Industry sources indicate that BOE is currently required to submit advanced panel samples for exhaustive testing. Should the manufacturer clear these hurdles, it is expected to enter the supply chain as a secondary or auxiliary vendor. In such a scenario, BOE’s initial shipment volumes would likely remain modest compared to Samsung Display’s commanding allocation, gradually scaling up only as production stability and yield consistency are proven over time.
Broader Ecosystem Projections: iPad Mini and iPad Pro Allocations
The anticipated 2027 iPad Air orders do not exist in a vacuum; they form part of a broader, multi-year supply chain strategy that encompasses almost the entirety of Apple’s tablet portfolio. Market forecasts indicate that Samsung Display is similarly positioned to supply an identical volume—approximately 4 million to 5 million OLED panels—for the next generation of the compact iPad mini.
Meanwhile, the high-end iPad Pro lineup, which famously pioneered OLED technology in Apple’s tablet category with its transition to tandem OLED architecture, is projected to command an annual demand of 3 million to 4 million panels. Unlike the consumer-focused iPad Air and iPad mini, the production responsibility for the premium iPad Pro panels is shared more evenly between South Korean heavyweights Samsung Display and LG Display.
This multi-tiered manufacturing allocation highlights the indispensable role that South Korean display industries continue to play in Apple’s hardware evolution. While mainland Chinese manufacturers like BOE are making aggressive strides to capture market share in standard and mid-tier device categories, South Korean suppliers maintain a technological moat in manufacturing complex, high-performance display architectures for Apple’s flagship tiers.
Technological Differentiation: Single-Stack OLED Versus Tandem OLED
A closer examination of the leaked supply chain specifications reveals a clear technological stratification between Apple’s product tiers. While the iPad Pro utilizes a sophisticated "tandem OLED" structure, the upcoming iPad Air and iPad mini are reportedly slated to adopt a more cost-effective "single-stack" OLED configuration paired with Low-Temperature Polycrystalline Silicon (LTPS) backplane technology.
To understand the engineering and market implications of this choice, one must examine the fundamental mechanics of display technology. Traditional Liquid Crystal Displays (LCDs), which still power the current generation of the iPad Air, rely on a uniform external backlight shining through a matrix of liquid crystals to produce images. While reliable and cost-effective, LCD panels inherently struggle to produce true blacks because the backlight remains partially active even in dark scenes, resulting in lower contrast ratios.
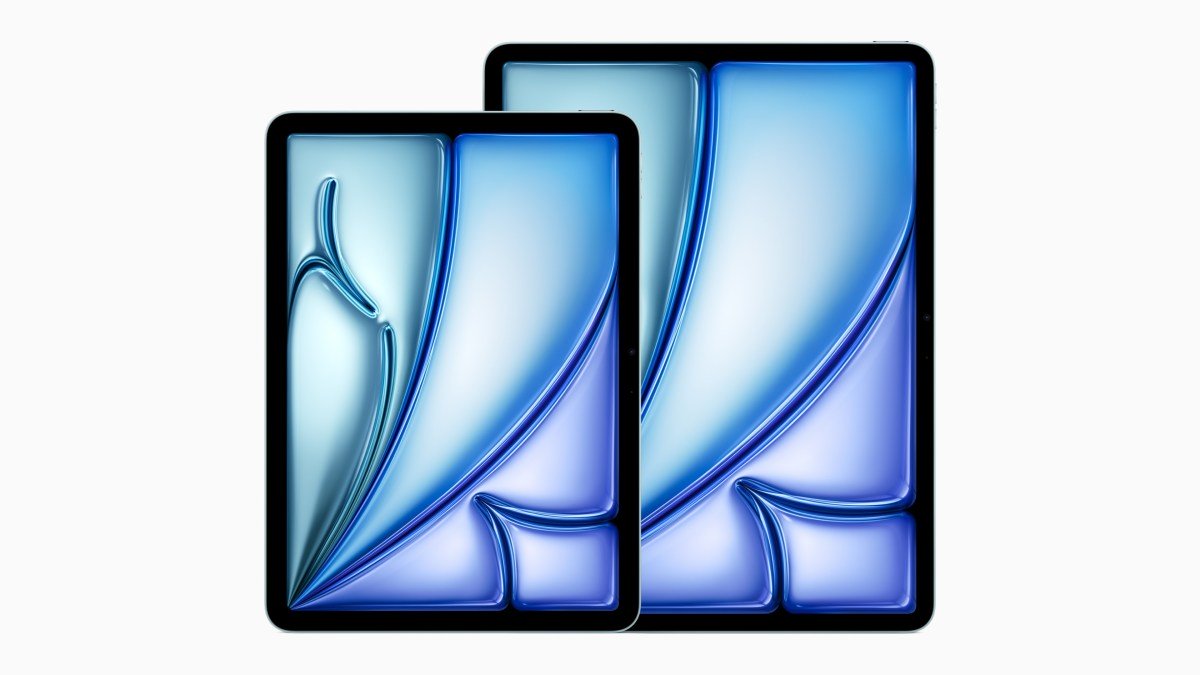
OLED (Organic Light-Emitting Diode) technology fundamentally revolutionizes this dynamic by allowing every individual pixel to generate its own light independently. When a pixel is instructed to display black, it simply switches completely off. This self-emissive property yields infinite contrast ratios, significantly deeper black levels, broader dynamic ranges, and exceptionally rapid pixel response times.
However, not all OLED panels are created equal. The single-stack architecture projected for the 2027 iPad Air utilizes one layer of organic light-emitting materials combined with LTPS backplane transistors. This approach provides all the fundamental visual benefits of OLED technology—such as superior contrast, vibrant color reproduction, and wide viewing angles—while remaining economically viable for a mid-tier price point.
By contrast, the premium iPad Pro utilizes a complex tandem OLED configuration featuring two distinct light-emitting layers alongside Low-Temperature Polycrystalline Oxide (LTPO) backplanes. The dual-stack structure enables dramatically higher peak brightness levels, improved power efficiency, and extended panel longevity under intensive professional workloads. The use of LTPO further grants variable refresh rates (ProMotion), scaling dynamically down to save battery life during static tasks.
This deliberate technological divergence ensures that Apple preserves a clear boundary between its product categories. The iPad Pro remains tailored for creative professionals and power users requiring absolute peak performance and specialized display metrics, whereas the iPad Air is positioned as a powerful, versatile, and more accessible option for mainstream productivity, education, and entertainment.
Chronological Context: The Evolution of iPad Display Technology
Tracing the trajectory of Apple’s tablet display evolution provides essential context for the 2027 iPad Air roadmap. For years, Apple maintained a strict segmentation across its iPad lineup: standard models and the iPad Air utilized IPS LCD Liquid Retina panels, while the iPad Pro series represented the cutting edge of mobile display technology.
The watershed moment in Apple’s tablet display strategy occurred with the release of the OLED iPad Pro models, which established a new industry benchmark for tablet screens. Following this high-end rollout, industry analysts widely anticipated a trickle-down effect that would eventually bring organic light-emitting diode technology to more affordable devices.
Current official specifications highlight that the iPad Air M4 generation—introduced to the market in March 2026—still firmly utilizes IPS-based Liquid Retina LCD technology. The 11-inch iteration features a native resolution of 2,360 by 1,640 pixels, while the larger 13-inch sibling boasts 2,732 by 2,048 pixels. Both variants support wide color (P3), True Tone technology, and full compatibility with the Apple Pencil Pro and Apple Pencil USB-C, maintaining a certified brightness ceiling of 500 nits for the 11-inch model and 600 nits for the 13-inch version.
Should the 2027 projections materialize, the transition to OLED will mark the most substantial structural upgrade to the iPad Air display architecture in its history. It will bridge the visual gap between the air and pro lineups, leaving the base-model iPad as the sole remaining stronghold for traditional LCD technology within Apple’s modern tablet portfolio.
Market Implications and Economic Outlook
The prospective shift of the iPad Air to OLED panels carries profound economic and competitive implications for the global consumer electronics market. For consumers, the democratization of OLED technology means that mid-tier buyers will soon enjoy the superior visual fidelity, energy efficiency, and immersive media consumption capabilities previously restricted to high-end device owners.
For component manufacturers, securing a spot in Apple’s supply chain represents a multi-billion-dollar revenue opportunity accompanied by intense operational pressure. Samsung Display’s anticipated dominance in the iPad Air supply chain reinforces its financial stability and manufacturing leadership. Meanwhile, BOE’s persistent efforts to clear Apple’s quality gates reflect the high stakes involved for Chinese manufacturers seeking to transition from supplying basic panels to capturing high-margin, premium consumer electronics contracts.
Despite the compelling nature of these industry reports, caution remains warranted. Supply chain forecasts are inherently fluid, subject to rapid shifts driven by macroeconomic conditions, manufacturing yield adjustments, component cost fluctuations, and evolving consumer demand patterns. Final product validation rests entirely within Apple’s internal testing protocols, meaning that commercial configurations and delivery timelines remain open to adjustment as 2027 approaches.
As the industry looks ahead, the anticipated introduction of the OLED iPad Air underscores Apple’s methodical approach to hardware iteration—systematically migrating advanced display technologies down its product ladder once manufacturing economies of scale and structural efficiencies reach maturity.

